One in four UK SMEs motivate employees with equity
One in four UK-based SMEs now share ownership with some or all of their employees, according to an independent study commissioned by Vestd and...
Founders, finance and people teams all rely on the same equity record - we just give each of them the view they need.
Watch a demoA short walkthrough, end to end.
Migrate to VestdDigitise or move your existing scheme
EMI, growth shares, CSOP & more
ValuationsUK HMRC & US 409A valuations
Equity management & adminGovernance, admin & filings
Fundraising - InVestd RaiseApply for S/EIS & structure your round
PISCES / secondary marketsDeploy into regulated secondary trading
This article is more than 7 years old. Some information may no longer be current.
Hallelujah! After nearly a six-week suspension, EMI schemes are back for UK SMEs.
A press release from the European Commission today stated:
State aid: Commission approves prolongation of UK Enterprise Management Initiative scheme
The European Commission has approved under EU State aid rules the prolongation of the UK Enterprise Management Initiative scheme, which reduces the taxation of employee share options for small and medium sized enterprises (SMEs). Under the scheme, employees of SMEs will benefit from reductions from income tax and/or national insurance contributions, when exercising their share options.
The aim of the scheme is to allow SMEs to recruit and retain employees, and thus enable their growth, without unduly distorting competition in the Single Market.
The Commission initially authorised the scheme in 2009. In March 2018, the UK authorities notified their plans to prolong the scheme to the Commission. The Commission’s assessment found that the prolongation of the measure is necessary to help UK SMEs attract and retain talented and skilled personnel. It also found that the measure contains a number of safeguards, such as a cap on the value of the share options that can be subject to the tax advantage both at the employee and employer level, ensuring that potential distortions to competition are limited. On this basis, the Commission concluded that the measure is in line with EU State aid rules. Without prejudice to any provisions of the Withdrawal Agreement, which is under negotiation, this Commission decision only applies until the UK ceases to be a Member State.”
So if you’ve been considering incentivising and rewarding your team with a company share options scheme, you can now do it in the most tax-efficient way (again).
Questions about company share schemes and EMI? Start with our Complete Guide to Setting Up a Company Share Scheme or contact us directly.
One in four UK-based SMEs now share ownership with some or all of their employees, according to an independent study commissioned by Vestd and...
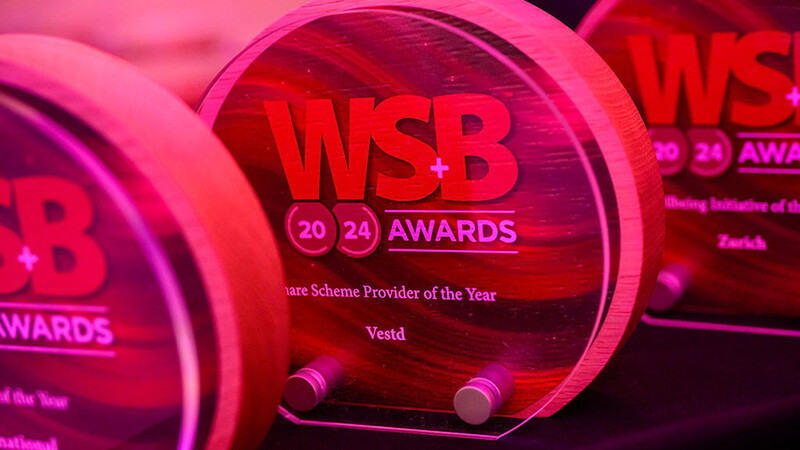
Vestd wins Share Scheme Provider of the Year at the WSB Awards 2024. Reinforcing our commitment to making sharetech accessible for UK businesses.
The number of companies operating employee share schemes is rising, and the Enterprise Management Incentives scheme is the main driver.